Play store

Bangladesh Bank has retained a cautious monetary policy stance for the October-December quarter, keeping its key policy rate unchanged at 9.50 percent as it seeks to support economic activity without disrupting the progress made in containing inflation.
The decision means the central bank has opted to observe economic developments for the time being rather than introduce another cut in interest rates, as underlying inflationary pressures and external risks remain significant.
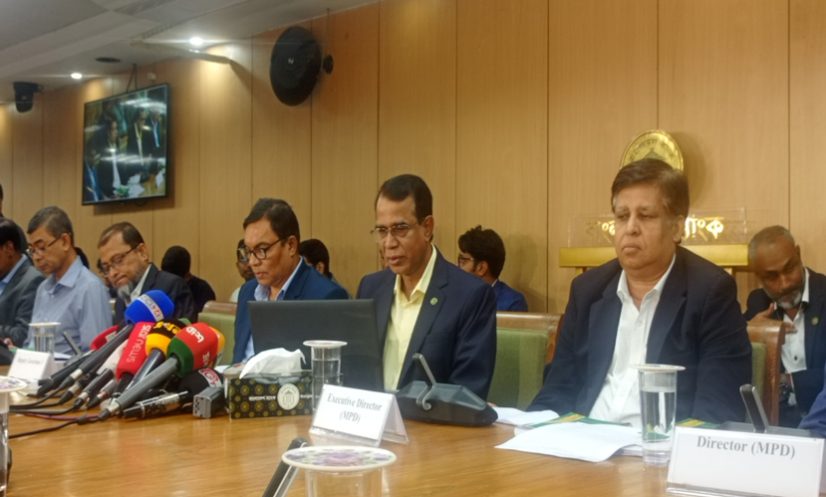
Bangladesh Bank Deputy Governor Habibur Rahman said at a press conference on Wednesday that the policy rate would remain at 9.50 percent. The Standing Lending Facility (SLF) rate has also been kept unchanged at 11 percent, while the Standing Deposit Facility (SDF) rate remains at 7.50 percent.
He said there would be no change in the central bank’s policy stance during the quarter, although recent macroeconomic developments presented a mixed picture.
Inflation had eased over the previous two to three months, he said, but uncertainty remained over whether the decline would continue amid recent domestic and international developments.
The Monetary Policy Committee (MPC), therefore, decided to observe the situation for another month or two before considering any further changes to policy rates, he said.
The decision followed the MPC’s 14th meeting on September 23. It was the first quarterly Monetary Policy Statement (MPS) issued after the central bank decided at its July 30 meeting to shift from a half-yearly to a quarterly monetary-policy framework.
Bangladesh Bank said the decline in headline inflation should not yet be viewed as sufficient evidence of a sustained easing of price pressures.
Headline inflation fell from 9.16 percent in June to 8.26 percent in August, its lowest level in 10 months, according to the MPS. Lower food inflation, which fell to 7.02 percent, was a major factor behind the decline.
However, non-food inflation remained high at 9.32 percent, indicating that underlying inflationary pressures were still strong.
The central bank identified several risks that could put renewed pressure on prices, including higher global energy prices, possible disruptions in the Strait of Hormuz, recent upward adjustments in administered energy prices and the potential impact of implementation of the new national pay structure.
Against this backdrop, Bangladesh Bank said it would continue to monitor both domestic and global developments before deciding on further monetary easing.
The cautious monetary stance comes at a time when economic activity remains subdued.
Bangladesh Bank estimated real GDP growth at 4.14 percent in FY2025-26, while growth in the third quarter of the fiscal year was only 2.2 percent. Industrial production also contracted by 0.28 percent during the period.
High-frequency indicators, including industrial and power generation, energy supply and private-sector credit, pointed to weak economic activity during FY2025-26. Some of these indicators, however, showed signs of modest recovery during the first quarter of FY2026-27.
The central bank said high financing costs, energy shortages, infrastructure constraints and uncertainty surrounding domestic and external demand could continue to weigh on economic growth.
It also noted that monetary policy alone could not resolve supply-side constraints. A Tk60,000 crore stimulus package, including Tk20,000 crore for reopening closed factories, along with refinancing schemes for agriculture, CMSMEs and export diversification, could support economic recovery.
The transmission of monetary policy has been relatively faster in financial markets, although its impact on the real economy remains limited.
Following the 50-basis-point cut in the policy rate in August, interbank interest rates and yields on government securities declined.
Weak private-sector credit demand, strong deposit growth and reduced willingness among banks to extend new loans, alongside increased investment by banks in government securities, contributed to the decline in yields.
Private-sector credit growth stood at only 4.75 percent in August, with weak investment demand, higher borrower risks and weaknesses in the banking sector cited as key factors. Current reporting also points to continued weakness in private-sector credit demand despite policy support.
The banking sector continues to face significant stress. According to the MPS, the ratio of non-performing loans reached 32.78 percent in June 2026.
Bangladesh Bank has therefore emphasised bank restructuring, stronger corporate governance, capital recovery and improved credit discipline as important elements of financial-sector reform.
The external sector recorded significant improvement in FY2025-26, with the balance of payments posting a surplus of $6.6 billion.
However, the overall balance moved into deficit during the first two months of FY2026-27, mainly because of a deficit in the financial account.
Higher remittance inflows provided some protection to the external sector. Remittances increased by 18.90 percent during the period, while relative stability in the exchange rate also helped contain imported inflation.
Bangladesh Bank expects economic recovery to remain gradual rather than rapid in the coming months.
Growth forecasts from international institutions also differ. The World Bank has projected Bangladesh’s growth at 4.6 percent in FY2026-27, while the International Monetary Fund has revised its earlier 4.3 percent forecast down to 3.5 percent.
The central bank expects inflation to gradually decline during FY2026-27 but sees considerable uncertainty over the pace of improvement.
It identified prolonged conflict in the Middle East, possible disruptions to supply through the Strait of Hormuz, high international prices of fuel and fertiliser, tighter global monetary conditions, domestic energy and infrastructure constraints, fiscal pressures, implementation of the national pay structure and weaknesses in the banking sector as major risks.
Against this backdrop, Bangladesh Bank said its key policy challenge would be to maintain the downward trend in inflation while supporting economic activity.
The central bank said it would make data-driven decisions after closely monitoring domestic and global developments, while placing emphasis on targeted credit support, structural reforms, financial-sector strengthening and orderly exchange-rate flexibility.
Its broader objective remains to support sustainable economic recovery while maintaining price stability, external-sector balance and the resilience of the financial system.