Play store

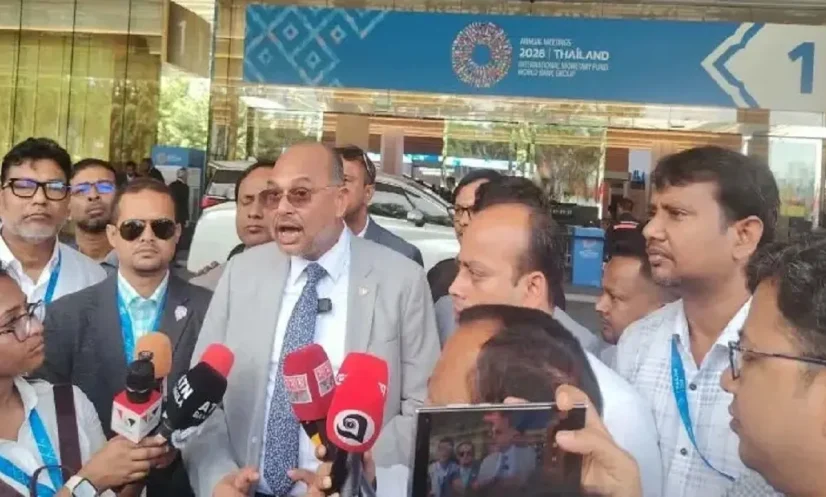
BANGKOK, October 12: The World Bank and the International Monetary Fund (IMF) have reached a policy consensus with the government on key economic reforms aimed at reviving the fragile economy, restoring discipline in the financial sector, increasing the tax-to-GDP ratio and creating jobs, Prime Minister’s Adviser on Finance and Planning Rashed Al Titumir has said.
He said the government’s economic reform roadmap, designed to meet public expectations, shares several core objectives with those of the multilateral development partners.
Speaking to journalists on the sidelines of the 2026 Annual Meetings of the IMF and World Bank Group in Thailand on Monday, Titumir also highlighted growing interest in investment from companies in China, Japan and the United States, as well as international investors.
He said the government was seeking financing from diverse sources to boost production and employment in Bangladesh.
Reopening closed factories, expanding social protection and managing rising energy sector costs are also among the government’s priorities, he added.
Titumir said the government had a politically defined roadmap to recover, rebuild and rapidly restructure the economy to put the country on a path to prosperity. The roadmap is outlined in a five-year economic strategy.
He noted that several fundamental aspects of the strategy align with reform proposals from the World Bank and the IMF.
According to Titumir, people want greater discipline in the financial sector, higher tax collection relative to gross domestic product (GDP), increased spending on social protection and job creation through industrialisation.
He said the public also expected closed factories to reopen, adding that these objectives were consistent with the World Bank’s reform vision.
The adviser emphasised that the government’s domestic reform agenda had broad policy alignment with international multilateral institutions.